India tightens its currency defences
Currency policy can shift costs between official reserves, bank funding and corporate cash flow. An initial exchange-rate move cannot settle its effectiveness.
By Global Bole News
Research and compilation
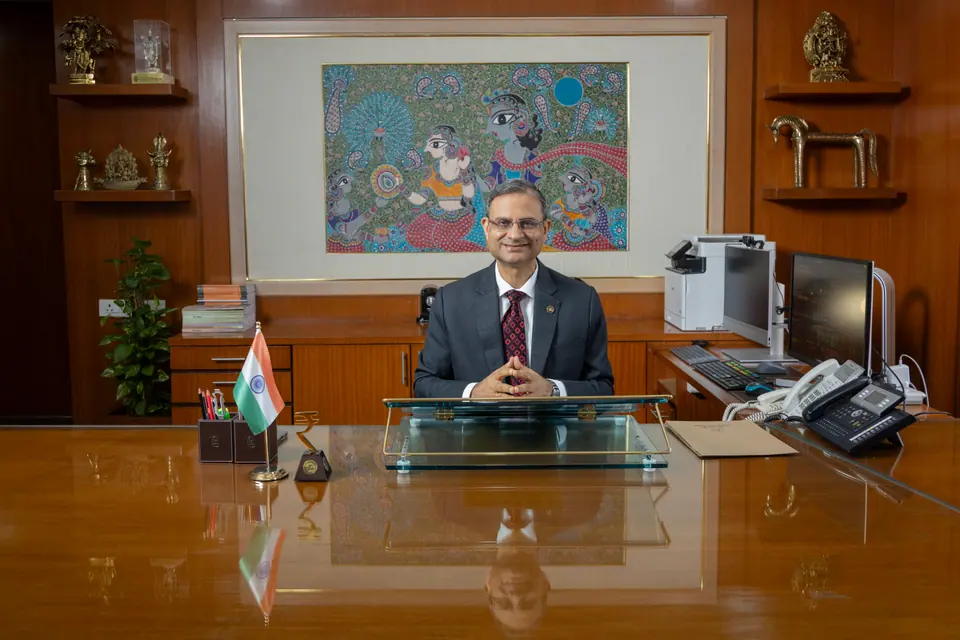
October 10: RBI tightens hedging and supplies dollars.1

RBI governor Sanjay Malhotra. Photograph: Nishikant Gamre Photography, © @nishikantgamre. Source: Reserve Bank of India; its media-use permission allows these photographs in RBI news coverage with source credit.
Moving a major buyer out of the market
From October 12, RBI will meet Indian Oil, Hindustan Petroleum and Bharat Petroleum’s entire daily dollar demand until further notice.2
The economic distinction is between removing a transaction from the open market and eliminating its underlying need. Oil still has to be paid for. A dedicated window changes the immediate supplier of foreign currency, potentially reducing competition for dollars among other buyers. It does not make the import bill disappear or independently improve the economics of importing oil.
That also changes how success should be judged. A calmer exchange rate would be one outcome; the amount of official foreign currency needed to achieve it would be another. The same visible stability could accompany very different pressures on the central bank’s balance sheet.
Verification and funding are separate tools
Aggregate outstanding no-proof caps fall from US$100m to US$5m, separately across dealers and exchanges. Cancelled rupee contracts cannot be rebooked; maturity rollovers remain permitted.3
Larger documented hedges remain allowed.1
For current-account FX-purchase hedges above US$2m entered after the directions’ issuance, banks must reserve 20% of rupee-equivalent notional in cash until termination.4 Dealers must obtain declarations against duplicate hedging.1
These distinctions matter to businesses comparing an ordinary import payment, a contract hedging that payment and a speculative position.
In practical terms, verification asks whether a financial position corresponds to an underlying obligation. A reserve requirement concerns the resources committed to holding the contract. Those mechanisms can reinforce one another, but they solve different problems. Better paperwork alone does not supply foreign currency, and a more expensive hedge does not remove the commercial risk it was intended to manage.
A market reaction is an early signal
Reuters reported a greater-than-7% rupee decline this year, followed by an approximately 0.6% offshore rebound after the announcement in thin trading.5
That initial response cannot establish a durable change in the balance of dollar supply and demand. Thin trading can make price moves a less complete indication of how the broader market will absorb new rules. The useful test comes as ordinary transactions resume and firms decide how much protection to buy under the revised framework.
The policy’s trade-off is consequently broader than whether the rupee rises on one occasion. Reducing pressure in one market may shift it toward official reserves, bank funding or corporate cash management. A lasting assessment needs those channels considered together, alongside the continuing foreign-currency needs of the real economy.
Source notes
-
2026-10-10 · RBI Announces Regulatory Measures for the Foreign Exchange Market · RBI ↩ ↩2 ↩3
-
2026-10-10 · RBI announces special window for Public Sector Oil Marketing Companies to meet dollar requirements · RBI ↩
-
2026-10-10 · Risk Management and Inter-Bank Dealings · RBI ↩
-
2026-10-10 · Risk Management and Inter-Bank Dealings - Foreign Exchange Risk Reserve · RBI ↩
-
2026-10-10 · India unveils tough curbs on dollar demand to defend rupee · Reuters / MarketScreener ↩